

Dynamic Yield Split
The core mechanism that powers Strata's risk-tranching protocol.
Overview
Strata’s Dynamic Yield Split (DYS) mechanism dynamically distributes realized yield from the underlying strategy between the senior and junior tranches. The mechanism references the underlying APY, benchmark rate, relative liquidity distribution between the two tranches and exogenously defined risk-premium parameters. This mechanism creates a natural balance between risk and reward, ensuring efficient capital utilization while maintaining stability and optmizing risk–reward.
TVL Ratios
Where:
and represent the total underlying asset deposits in the senior and junior tranches, respectively.
These ratios determine the distribution of yield and risk between the two tranches. A higher senior TVL ratio indicates greater demand for safety, which increases the risk premium paid to the junior tranche.
Benchmark Rate
Senior tranche offers a minimum guaranteed APY tied to the benchmark rate, which is different for each market. For e.g., the current benchmark rate for Ethena USDe market is supply-weighted average of USDC and USDT lending rates on Aave v3 Core market, calculated as:
Senior Tranche Yield
Where:
: Yield of the underlying asset (e.g., sUSDe).
: Minimum guaranteed APY of the senior tranche linked to the benchmark rate.
: Percentage of the paid by the senior tranche to the junior tranche for the risk coverage.
Risk Premium
Where:
: Baseline risk premium that senior tranche pays to the junior tranche.
: Maximum additional premium applied that may be applied as the increases.
: Exponential scaling factor controlling the additional premium growth with the .
As more liquidity flows into the senior tranche, the increases, pushing the risk premium higher — rewarding junior tranche with higher yields for absorbing more risk.
Ethena USDe
10%
12.5%
0.3
Neutrl NUSD
15%
15%
0.3
Midas mHYPER
12.5%
15%
0.3
Midas mM1-USD
12.5%
15%
0.3
Saturn USDat
100%
0%
0.3
Hastra PRIME
5.0%
7.5%
0.3
Junior Tranche Yield
The junior tranche receives:
The base yield from the underlying source, plus
The risk premium paid by the senior tranche, scaled by the TVL ratio between tranches.
This structure amplifies returns for the junior tranche, providing leveraged upside to the underlying yield.
Senior Coverage and Junior Overperformance
The senior tranche is backed by additional coverage from the junior tranche and, in exchange, receives a leveraged yield relative to the underlying APY, determined as follows:
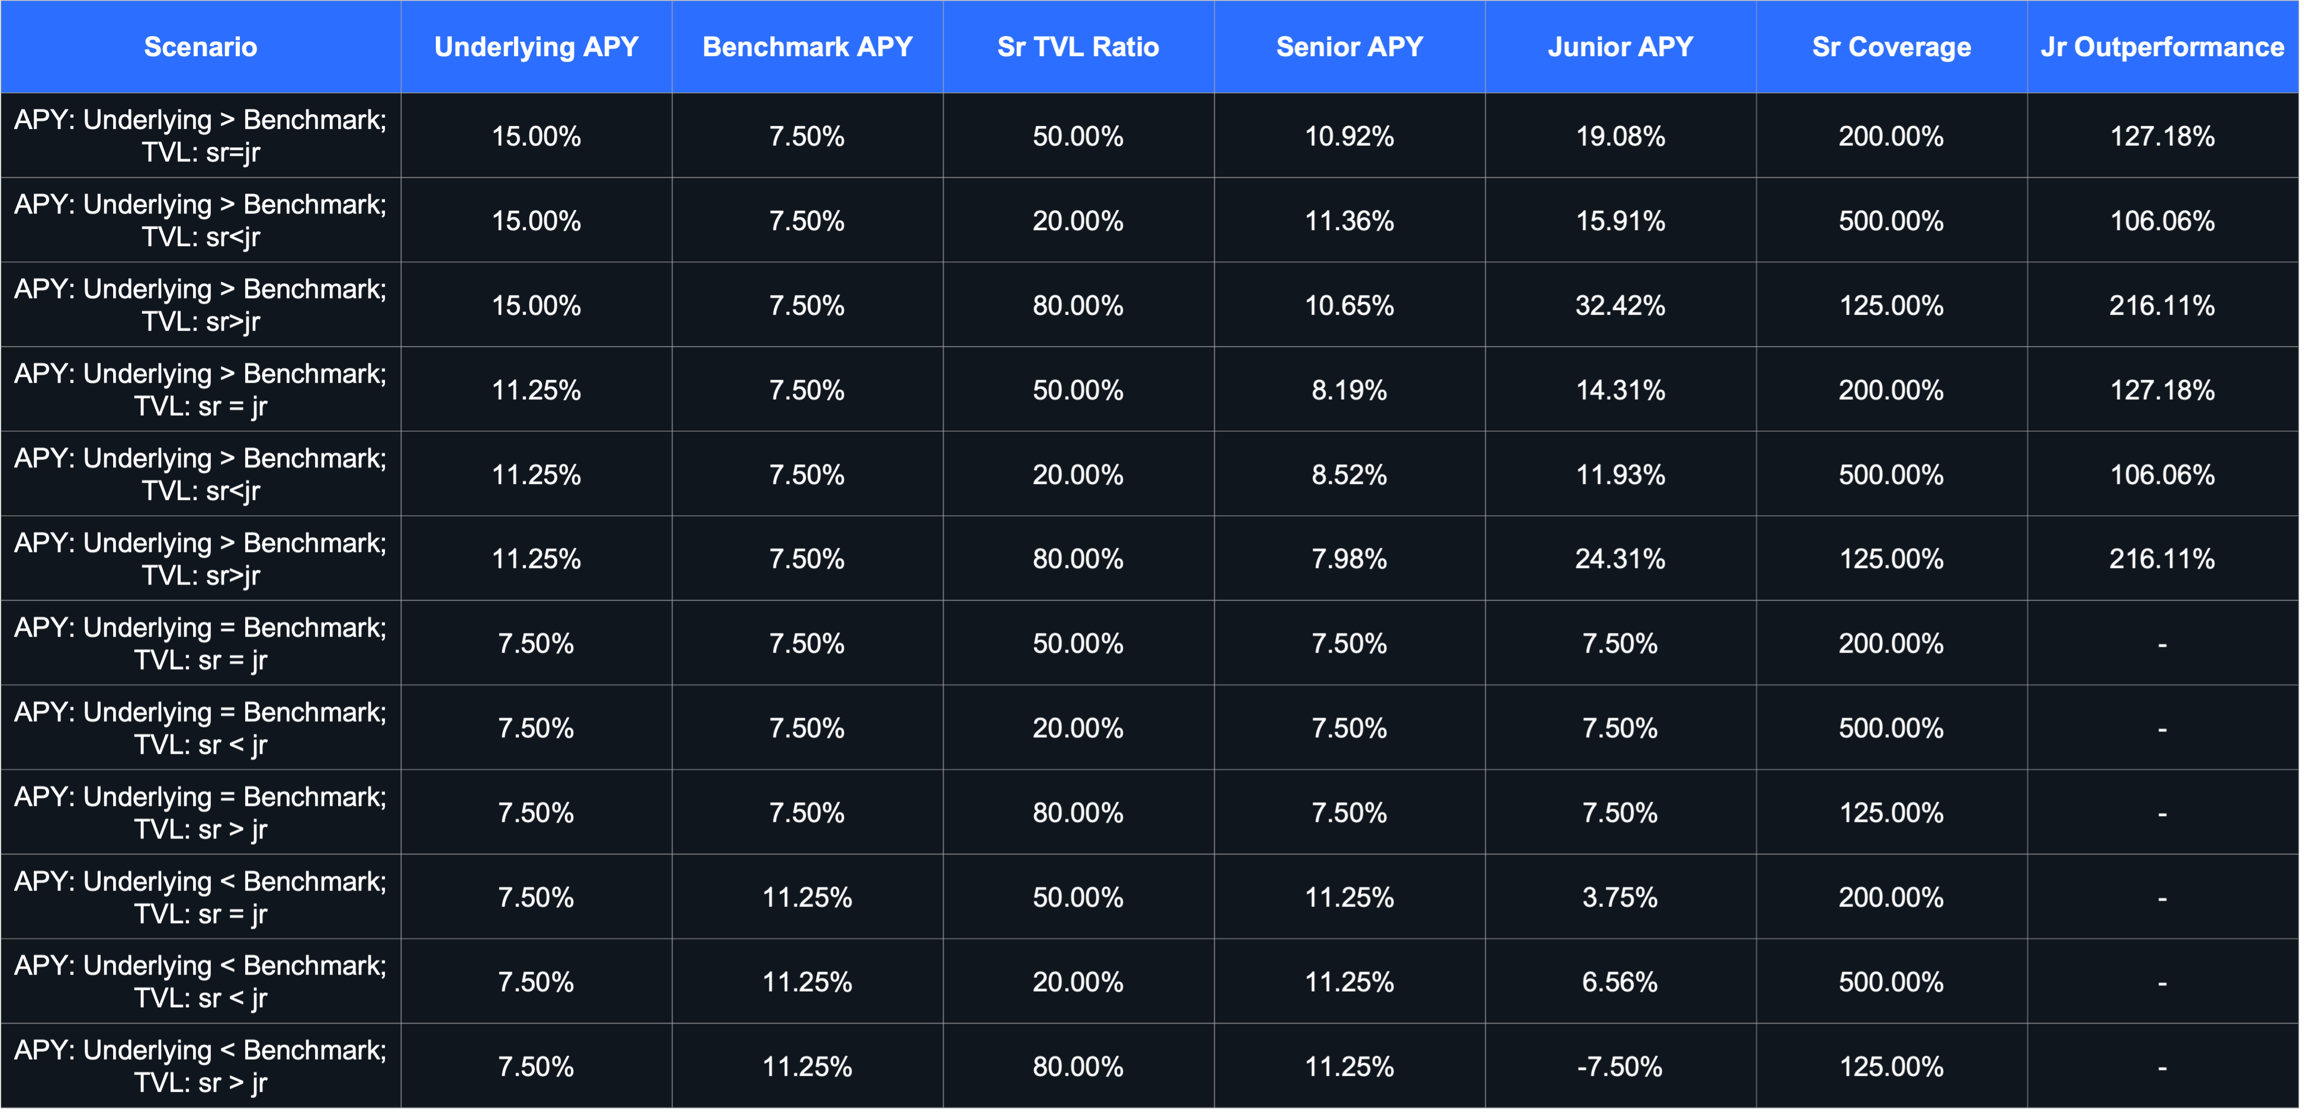
Senior & Junior APY Simulations
The table below shows the estimated APYs of senior and junior tranches under different underlying APY, benchmark rate and senior TVL ratio scenarios assuming x=15%, y=15% and k=0.3.
Last updated